Insurance Roof Claim Dothan AL
The adjuster works for the insurance company. We work for you — free documentation, on-site representation, and denial appeal support since 1991.
Why the Order Matters More Than People Realize
The insurance adjuster who inspects your roof works for the insurance company, not for you. Homeowners who get independent documentation before the adjuster's visit consistently receive more complete claim approvals than those who face the adjuster alone. MAC Construction provides free storm damage documentation, attends your adjuster meeting at no charge, and helps with denial appeals — most Dothan homeowners with proper documentation end up paying only their deductible.
Page Summary — Last Verified August 2026
MAC Construction represents Dothan homeowners through the insurance claim process — documentation, adjuster meeting attendance, and appeal support if a claim is underpaid or denied.
- All insurance claim assistance is free — no separate charge, whether or not you hire us for repairs
- Most Alabama policies require claims filed within one year of the storm date
- We attend adjuster meetings and advocate for a complete damage scope, not just the obvious items
Figures from MAC Construction's own 2026 job records and the live Google Business Profile (4.9★, 106 reviews), verified August 2026.
Hundreds of Claims, One Consistent Pattern
Stephen McDuffie has guided hundreds of Dothan homeowners through insurance claims since 1991. The pattern is consistent: homeowners who get professional documentation before calling their insurer receive more complete settlements than those who call their insurer first and scramble for evidence afterward.
"The adjuster's job is to evaluate damage on behalf of the insurance company — that's not a criticism, it's just the structure of the relationship. Having someone in your corner who knows what to point out changes the outcome."
This assistance is free whether or not you ultimately hire us for repairs — the documentation and adjuster meeting attendance cost nothing, because getting your claim right matters more than which contractor does the work.

AL License #30154 · Est. 1991
Call a Contractor Before You Call Your Insurer
Once the adjuster visits your property, the narrative of your claim is largely set.
| What Happens | Contractor Called First | Insurer Called First |
|---|---|---|
| Documentation | Complete, before adjuster arrives | Scrambled together after the fact |
| Adjuster Visit | Contractor present, points out full scope | Homeowner faces adjuster alone |
| Damage Missed | Unlikely — documented first | Common — no baseline comparison |
| Settlement Completeness | Typically more complete | Often underpaid on first offer |
This isn't about delaying your claim — call us the same day you notice damage, and we'll typically have documentation ready before your adjuster even schedules a visit.
What's Included in Our Insurance Claim Assistance
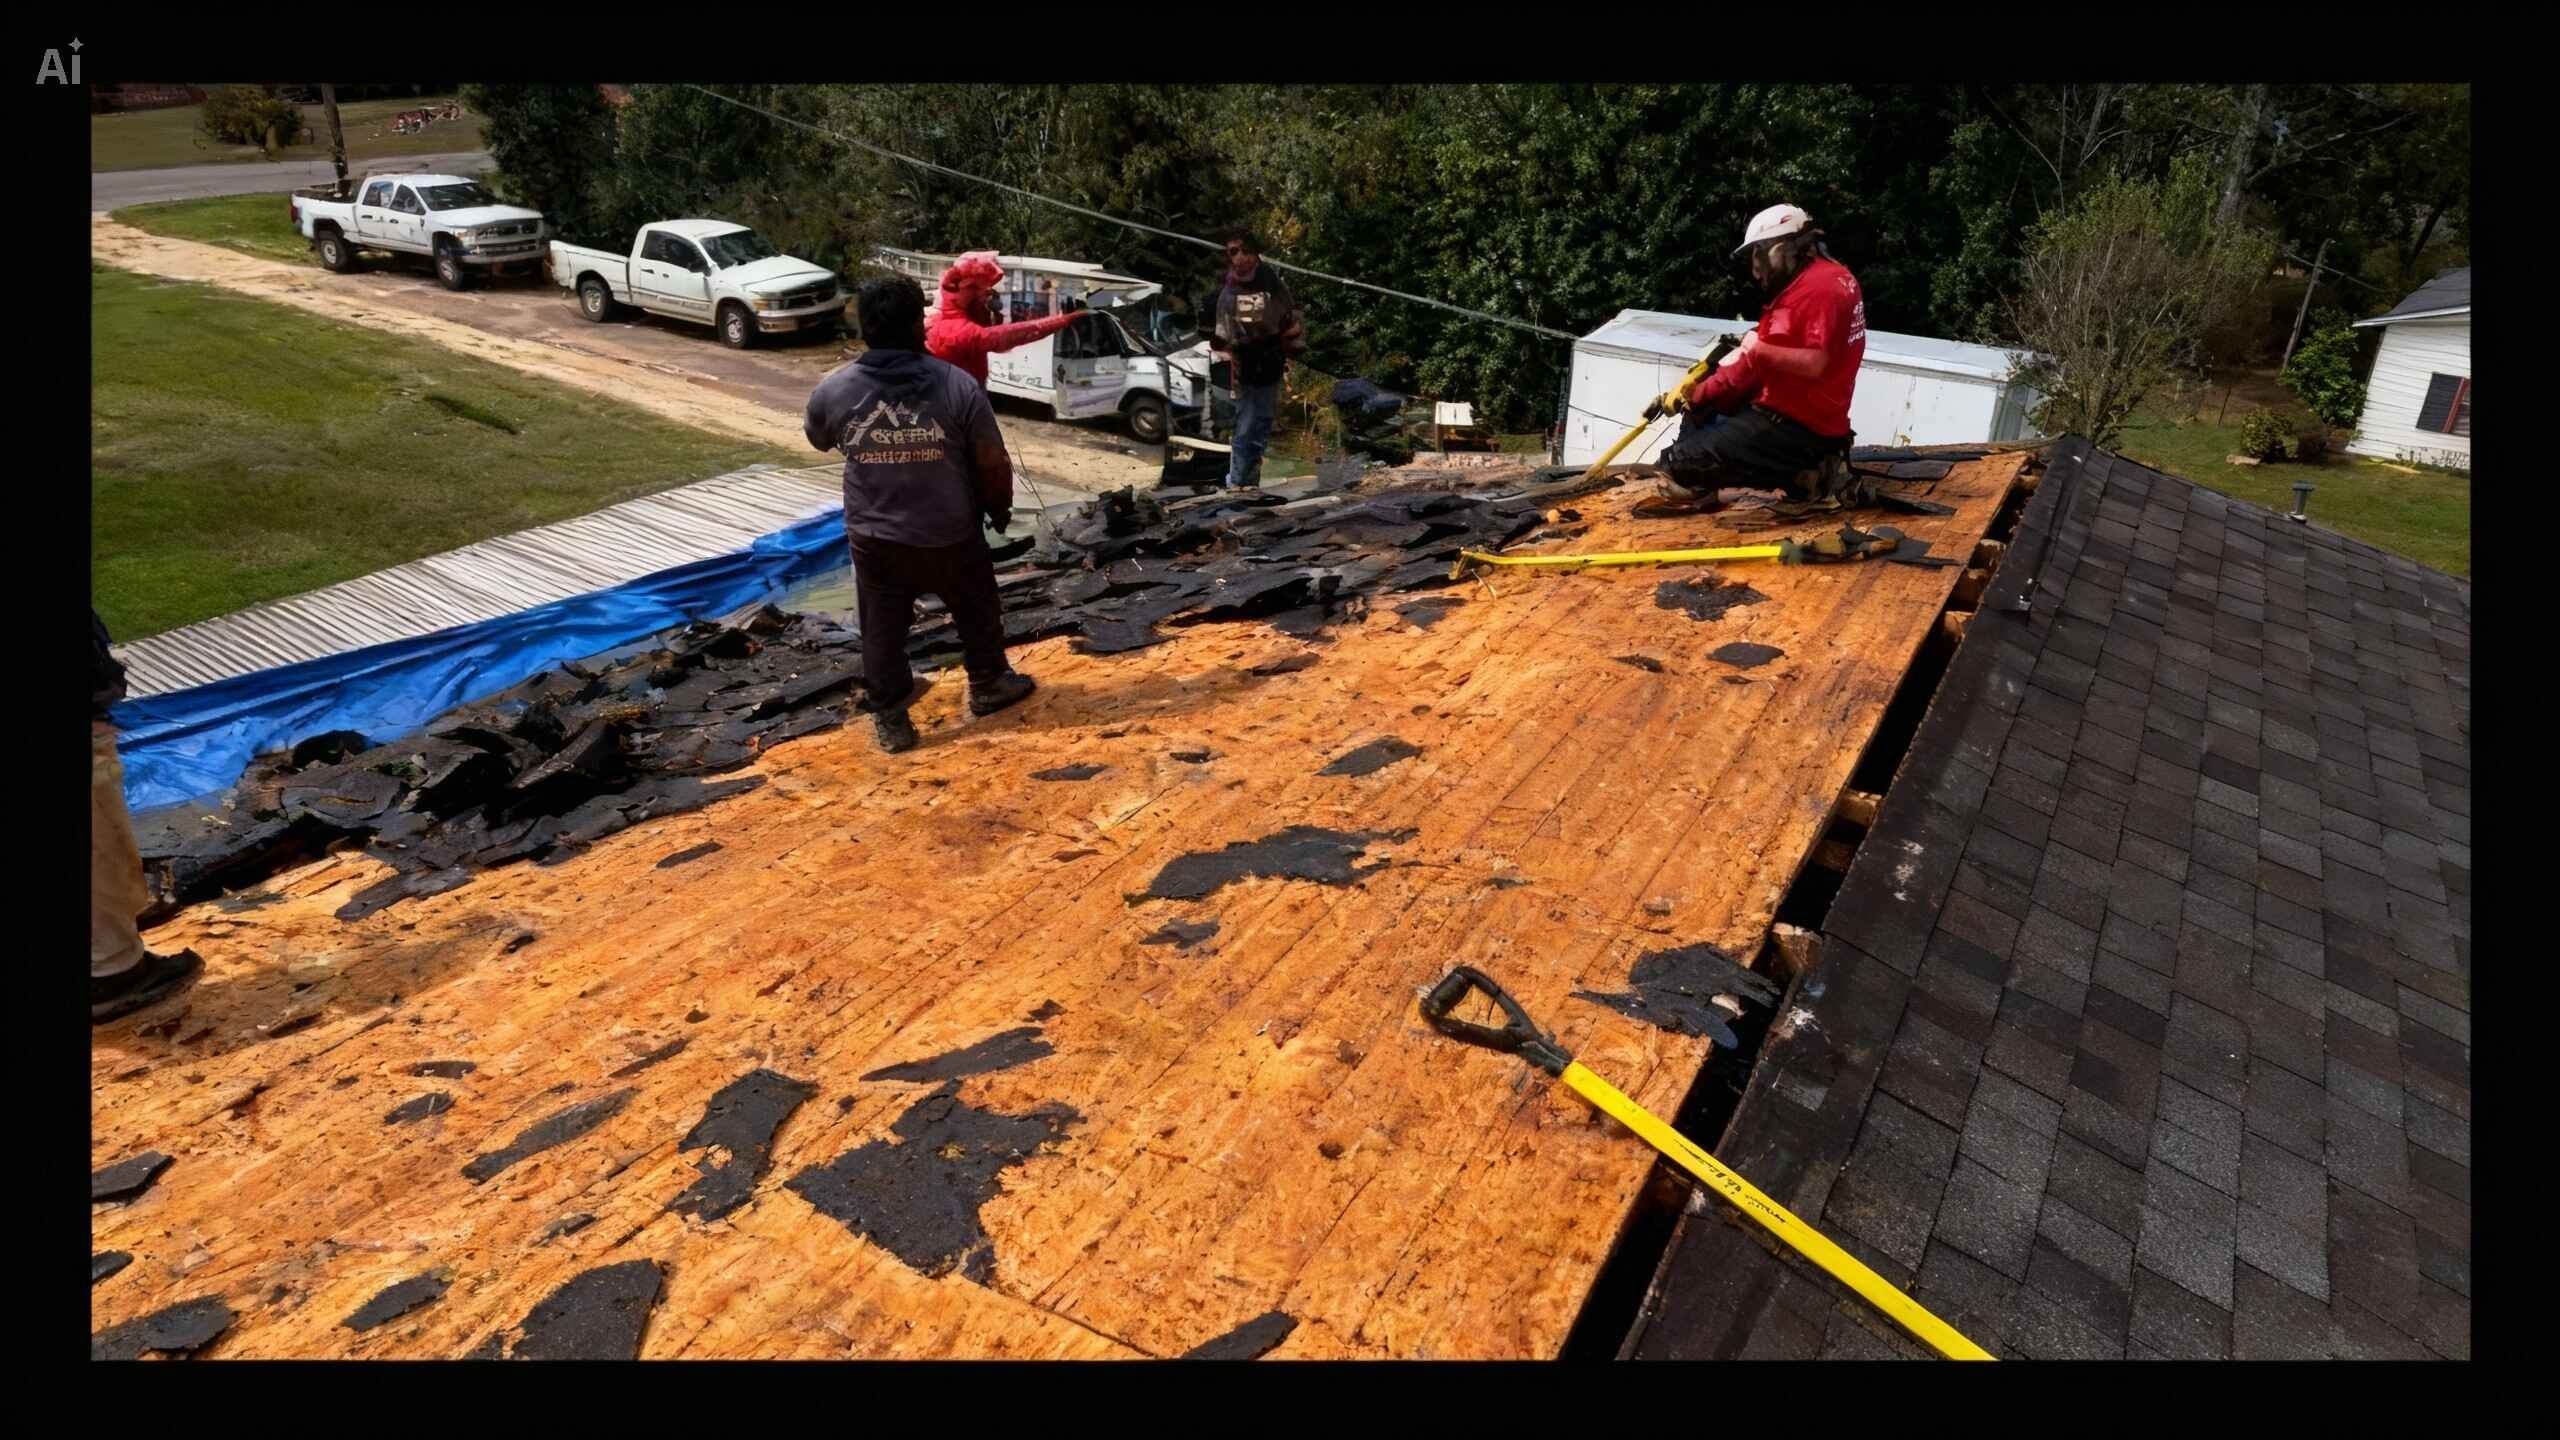
Per-impact hail documentation, wind-lift patterns, and flashing damage — photographed and dated, formatted for insurance submission.

We walk the roof with your adjuster, pointing out damage that's easy to miss from a ground-level or rushed assessment.

If damage is discovered once repair work begins, we document it and help file a supplemental claim rather than absorbing the cost.
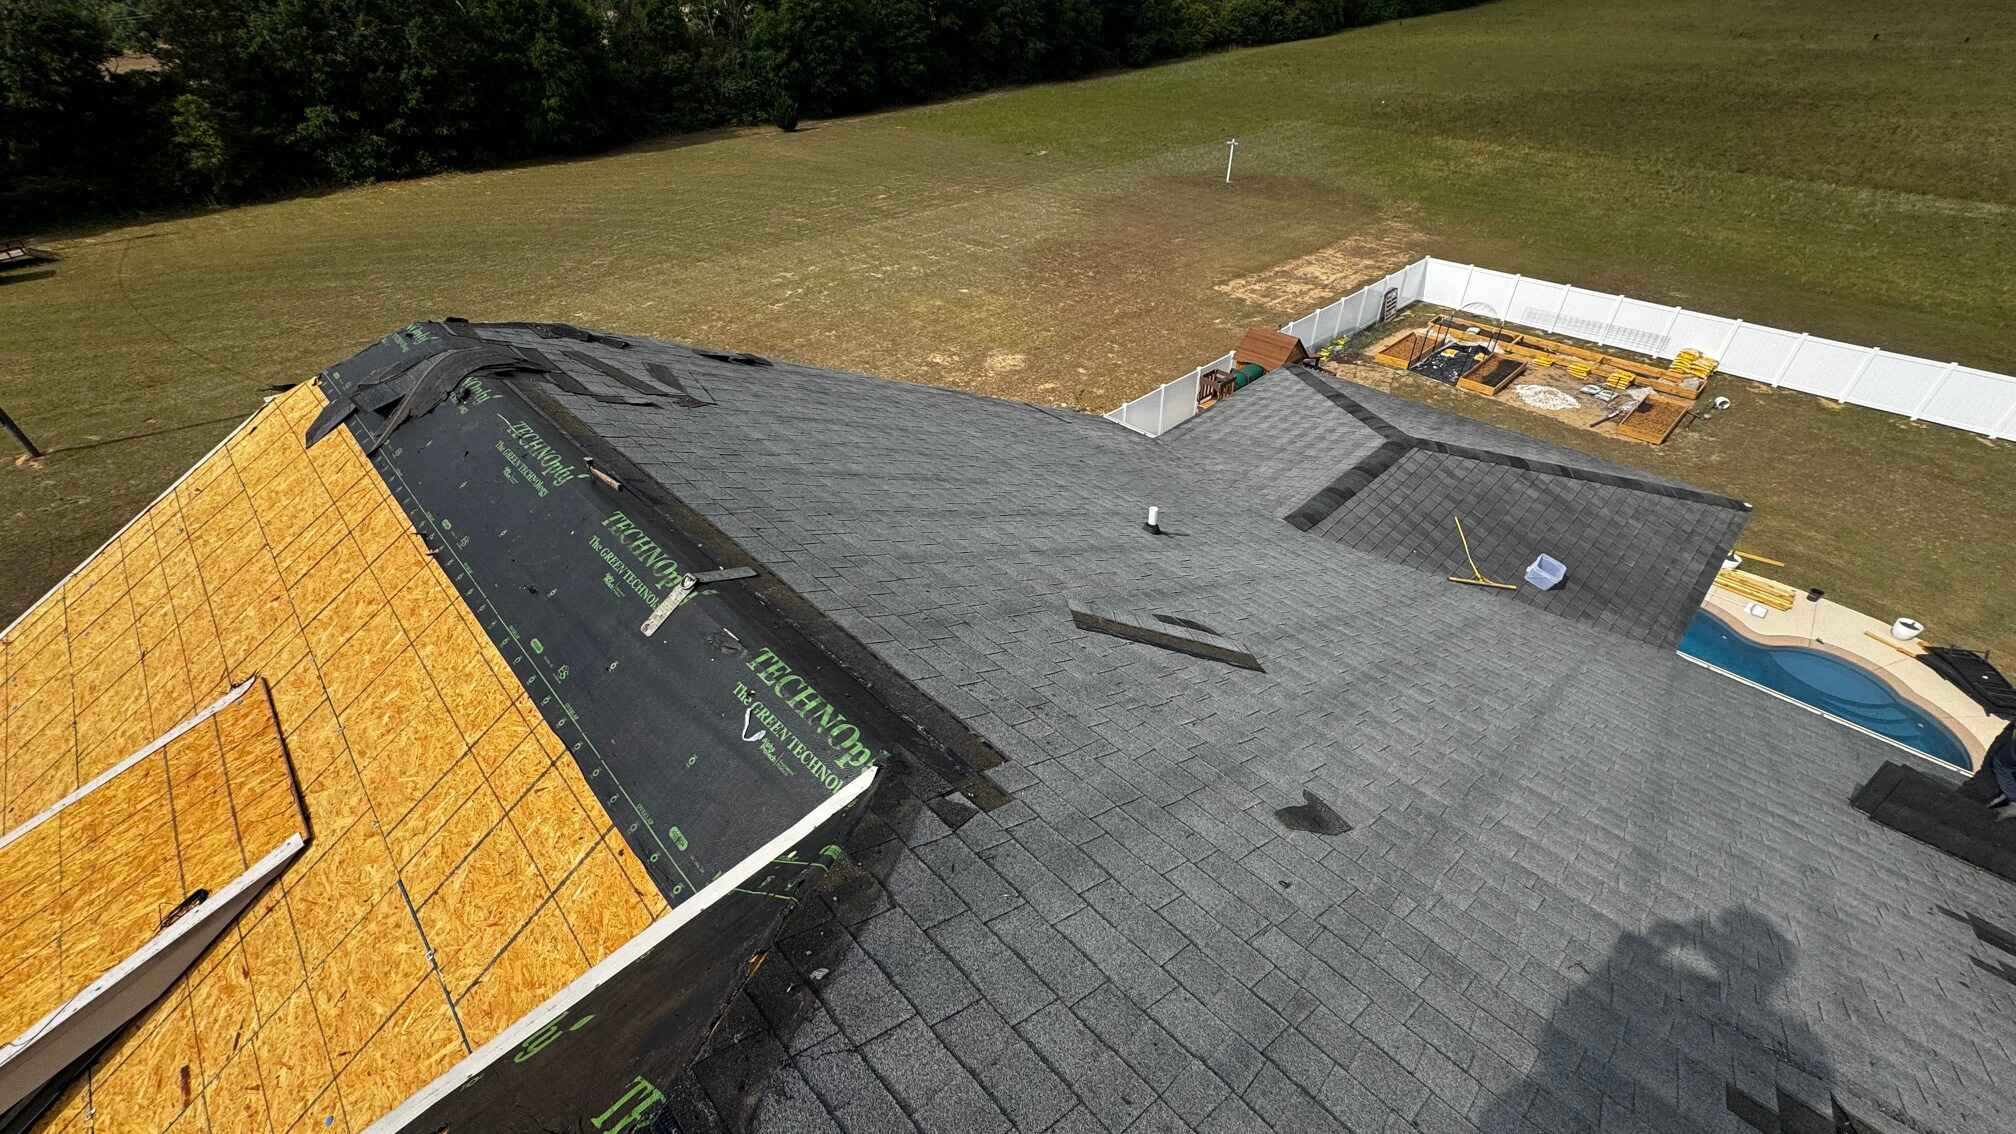
If your claim is underpaid or denied, we help you understand why and provide additional documentation to support an appeal.
Insurance Terms Worth Understanding
A few terms that show up in almost every Alabama roof claim.
What it costs to replace your roof today, at current material and labor prices — the full amount your policy ultimately pays if you have RCV coverage.
RCV minus depreciation for your roof's age. Insurers typically pay ACV first, with the depreciated amount recoverable after repairs are completed and documented.
The difference between ACV and RCV — money you're entitled to once repairs are complete, but only if you submit the final invoice. Many homeowners never claim it.
An additional claim filed when damage is discovered after the initial adjuster visit — common once decking is exposed during repair.
A contractor offering to "waive your deductible" is illegal insurance fraud in Alabama — a red flag for any roofer making that offer.
If Your Claim Is Denied or Underpaid
The most common reasons claims get denied — and what actually helps.
The most common denial reason. Our per-impact documentation with dates ties damage to a specific, identifiable storm event — the key evidence insurers require.
We provide a complete damage scope, not just the obvious impacts, so the assessed cost accurately reflects everything affected.
Most Alabama policies require claims within one year of the storm date. If you're near that deadline, call us immediately — we can often turn documentation around same-day.
We provide our own detailed, itemized repair estimate to compare against the adjuster's — often the basis for a successful supplemental claim.
You always have the right to request a re-inspection or escalate to the Alabama Department of Insurance if you believe a claim was handled unfairly.
Our Insurance Claim Assistance Process
Call Us First
Before contacting your insurer, call 334-726-6401 — we aim to document within 48 hours of your storm event.
Complete Documentation
Every impact photographed and dated, formatted the way Alabama adjusters expect to see it.
You File the Claim
With our documentation in hand, you contact your insurer to open the claim — typically stronger footing than filing blind.
We Attend the Adjuster Meeting
At no charge — walking the roof together, pointing out the full scope of damage.
Repair Once Approved
Binding written quote for the approved scope, with your signed 5-year workmanship warranty at completion.
Insurance Claim Repairs Across Dothan & the Wiregrass
6 different completed projects that started as an insurance claim — every one is our own work.


What Dothan Homeowners Say
 ★★★★★
"MAC Construction guided us through the entire insurance claim. Handled all documentation and attended our adjuster meeting. We ended up paying only our deductible for a full replacement. True professionals."
★★★★★"Our first adjuster visit resulted in a lowball estimate for spot repairs. MAC came out, documented the full scope, met with the adjuster on a re-inspection, and got it upgraded to a full replacement claim."
★★★★★"Didn't realize I needed to submit a final invoice to recover the depreciation my insurer held back. MAC explained the whole ACV vs RCV thing and made sure we actually got that second check."
Credentials You Can Verify Yourself
Any contractor representing you in an insurance claim should carry a valid Alabama license — verifiable free at hblb.alabama.gov. Never work with a contractor who offers to waive your deductible — that's insurance fraud in Alabama.
MAC Construction
Dothan, AL 36305
Get Your Free Claim Documentation
We aim to document within 48 hours. Stephen responds directly.
Insurance Roof Claim Dothan AL — Your Questions Answered
Yes, completely free — documentation, adjuster meeting attendance, and appeal support cost nothing, whether or not you hire us for the actual repair.
Call a contractor first for documentation, then file with your insurer. Homeowners who document first consistently receive more complete settlements than those who file blind and scramble for evidence afterward.
Most Dothan homeowners with complete, professional documentation pay only their deductible for covered storm damage. Outcomes vary by policy and damage extent — we'll give you an honest read on your specific situation.
Many policies pay Actual Cash Value first, holding back depreciation until repairs are complete. You must submit your final invoice to recover that second payment — many homeowners don't realize this and never collect it. We make sure you do.
No — and any contractor offering to do this is committing insurance fraud under Alabama law. We will never make that offer, and we'd encourage you to avoid any contractor who does.
We can still help. We provide independent documentation and an itemized repair estimate to support a re-inspection request or appeal — many denials are reversible with better evidence.
Most Alabama homeowners policies require claims within one year of the storm date. If you're near that deadline, call us immediately — we prioritize time-sensitive documentation.
Yes. We've managed commercial insurance claims for Wiregrass businesses, ensuring claims are documented at full scope with irrefutable evidence.
A supplemental claim covers damage discovered after the initial adjuster visit — common once decking is exposed during repair. We document and help file these so the extra cost isn't yours to absorb.
Yes. Alabama Contractor License #30154, held continuously since 1991, verifiable at hblb.alabama.gov.
Everything Else Worth Reading First
Not a sitemap — just what actually helps if you're navigating a claim right now.
Don't Face the Adjuster Alone
Free documentation, free adjuster representation, denial appeal support — before your claim window closes.
AL License #30154 · 6,000+ Roofs Since 1991 · 4.9★ from 106 Google Reviews